Auto Leasing Program

A lease is four numbers. You are shown one.

Money factor, residual, capitalized cost, term. Two are where the work happens, one is fixed by the lender, one is yours. The monthly payment is only what they produce.

CarOracle represents the lessee. We check the money factor against the lender's published rate and work the capitalized cost, which are the two numbers a quote does not show you.

Schedule a Consultation

Complimentary · 15 minutes

5.0

across 85 client reviews on Google and Yelp

66 on Google, 19 on Yelp, as of September 3, 2026.

Money factor

The lender publishes a base rate each month. A dealer may quote above it, which raises your payment without changing the car, the incentives or the residual. A marked-up quote looks identical to a competitive one.

Residual value

The lender's projection of what the car is worth at lease end, as a percentage of MSRP. Set monthly by model, trim, term and mileage. Nobody negotiates it, and a higher one lowers your payment.

Capitalized cost

The price the lease is written on, plus anything rolled into it. This is the same negotiation as a purchase, and it is the one most lessees never have because the conversation is about the payment instead.

Term and mileage

Yours to decide, and the decision moves the payment more than most people expect. We work the lender's menu of terms and mileage tiers against how the car will actually be driven.

Multiply the money factor by 2,400.

That is the approximate APR you are being charged. Compare it to the lender's published base rate for that model, term, and credit tier, and you can see the markup. We run this on every worksheet, along with the residual, the capitalized cost, and every fee by name. Programs change monthly. A structure that existed in June may not exist in July on the same car at the same price.

0.00310 ≈ 7.4% APR
Money factor, quoted, multiplied by 2,400
Illustrative figures. The gap is markup, it is negotiable, and it is invisible on a payment quote.
0.00215 ≈ 5.2% APR
Lender base rate, multiplied by 2,400
Lender base rate, published.

Four numbers set the payment. Three things set the outcome.

The tax compounds across cars, not within one

California gives no sales tax credit for a trade-in, so a purchaser pays tax on the full price every time. At an average new vehicle transaction price near $50,000, and rates running from 7.25 percent statewide to 11.25 percent in parts of Los Angeles County, that is roughly $3,600 to $5,600 per cycle, paid again on the next car. A lease taxes the payment stream instead. The cost is invisible on your first car and obvious by your third.

Cox Automotive, average new vehicle transaction price, July 2026, US. California Department of Tax and Fee Administration, city and county rate table effective July 1, 2026.

The term decides how long you stay underwater

Once tax, fees and first-year depreciation land, any financed purchase is worth less than the balance. That is true of every loan. What the term changes is how long it stays true. New loans at 61 to 72 months originate near 116 percent of value; at 73 to 84 months, near 129 percent, and nearly a third of new loans now sit in that longer bucket. A buyer who replaces on a four year cadence while financing on a seven year one is trading while still in the hole and carries the difference into the next car. A lease prices that exit at signing.

Experian, State of the Automotive Finance Market, Q2 2026. New vehicle loans, US: average loan term distribution and average loan to value at origination.

The option is yours to exercise, not to sell

If the car is worth more than the residual at lease end, you can buy it at the lower number. What you mostly cannot do is flip it. Many captive lenders now restrict payoff to the lessee or a same brand dealer, which closed the third party buyout. California then taxes the buyout, roughly $2,200 to $3,400 on a $30,000 residual depending on where the car is registered. The equity is real. It is less liquid than it looks.

California Department of Tax and Fee Administration, city and county rate table effective July 1, 2026. Payoff eligibility varies by lender and is confirmed per transaction.

What it costs

The numbers that do not move

One of these is what we cost. The other is who is accountable for it.

Money factor and capitalized cost are where a lease is won or lost. That is the work this fee pays for.

Schedule a Consultation

Complimentary · 15 minutes

$299
One fee, whatever the vehicle. It does not scale with the price of the car.
43082
California dealer license, autobroker endorsement. Verifiable with the California DMV.

A Selection of Vehicles We Have Brokered for Clients
  • 2026 silver BMW i4
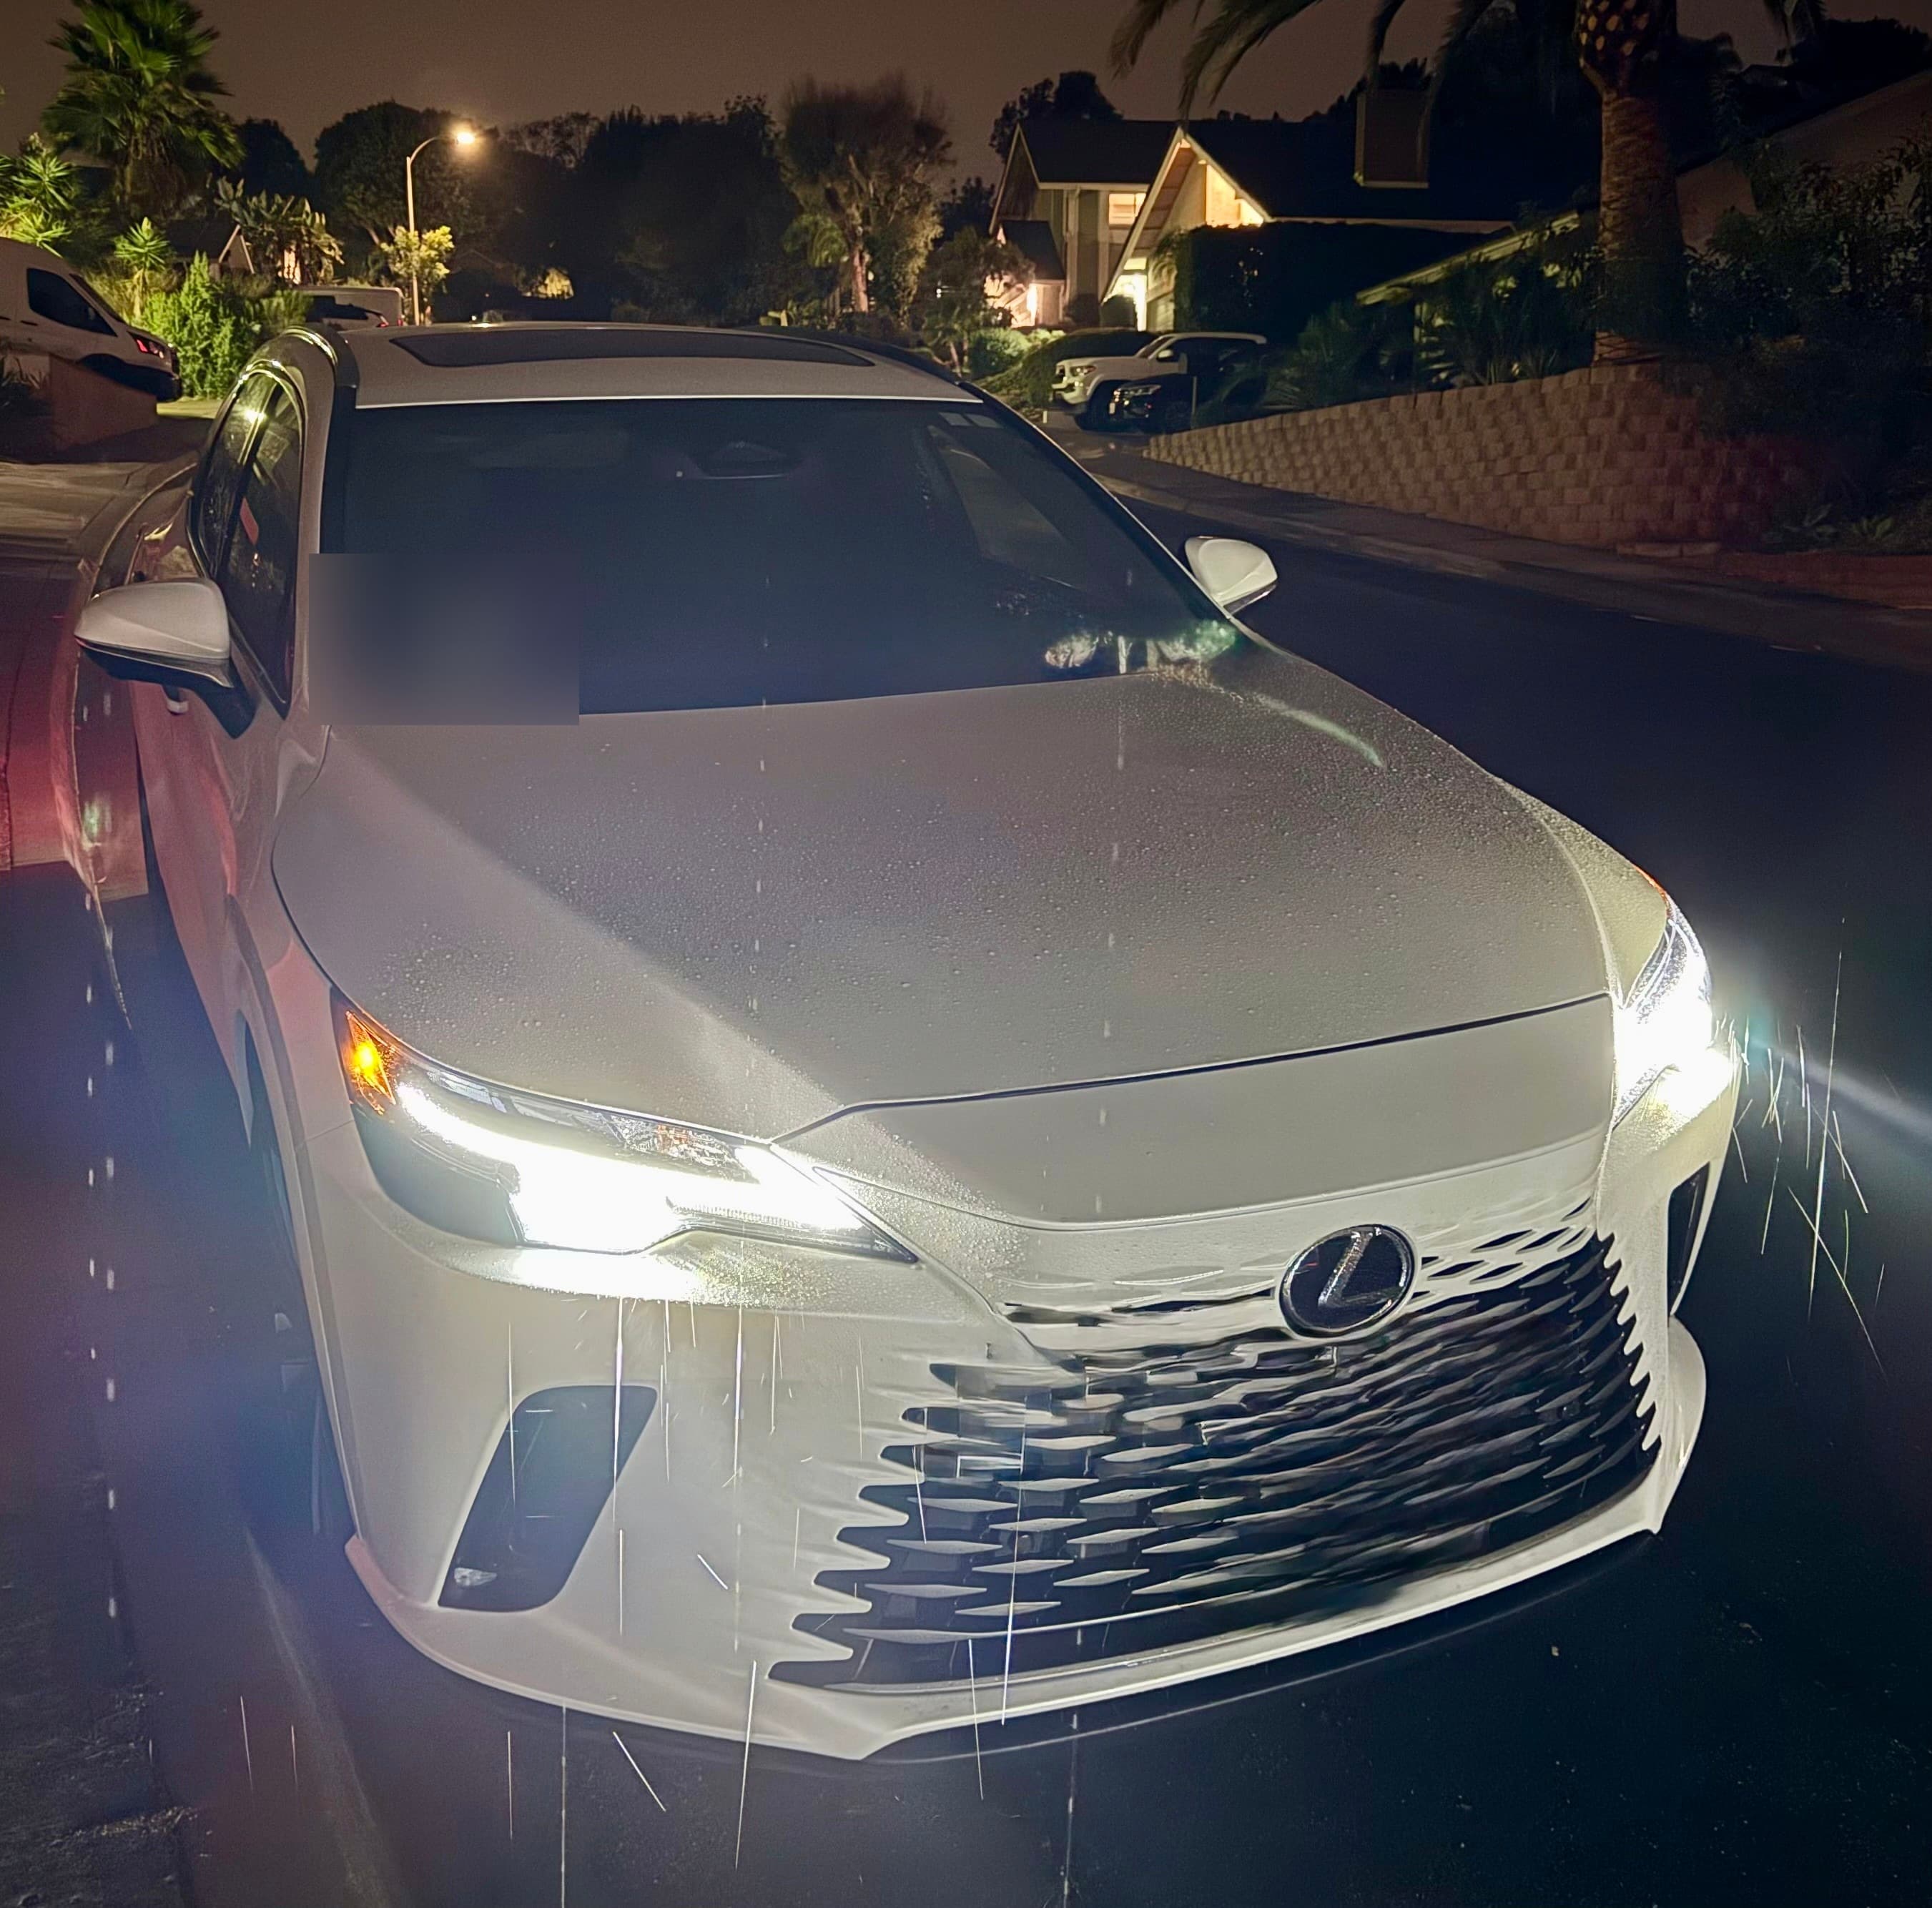
  • 2026 white lexus RX residential delivery
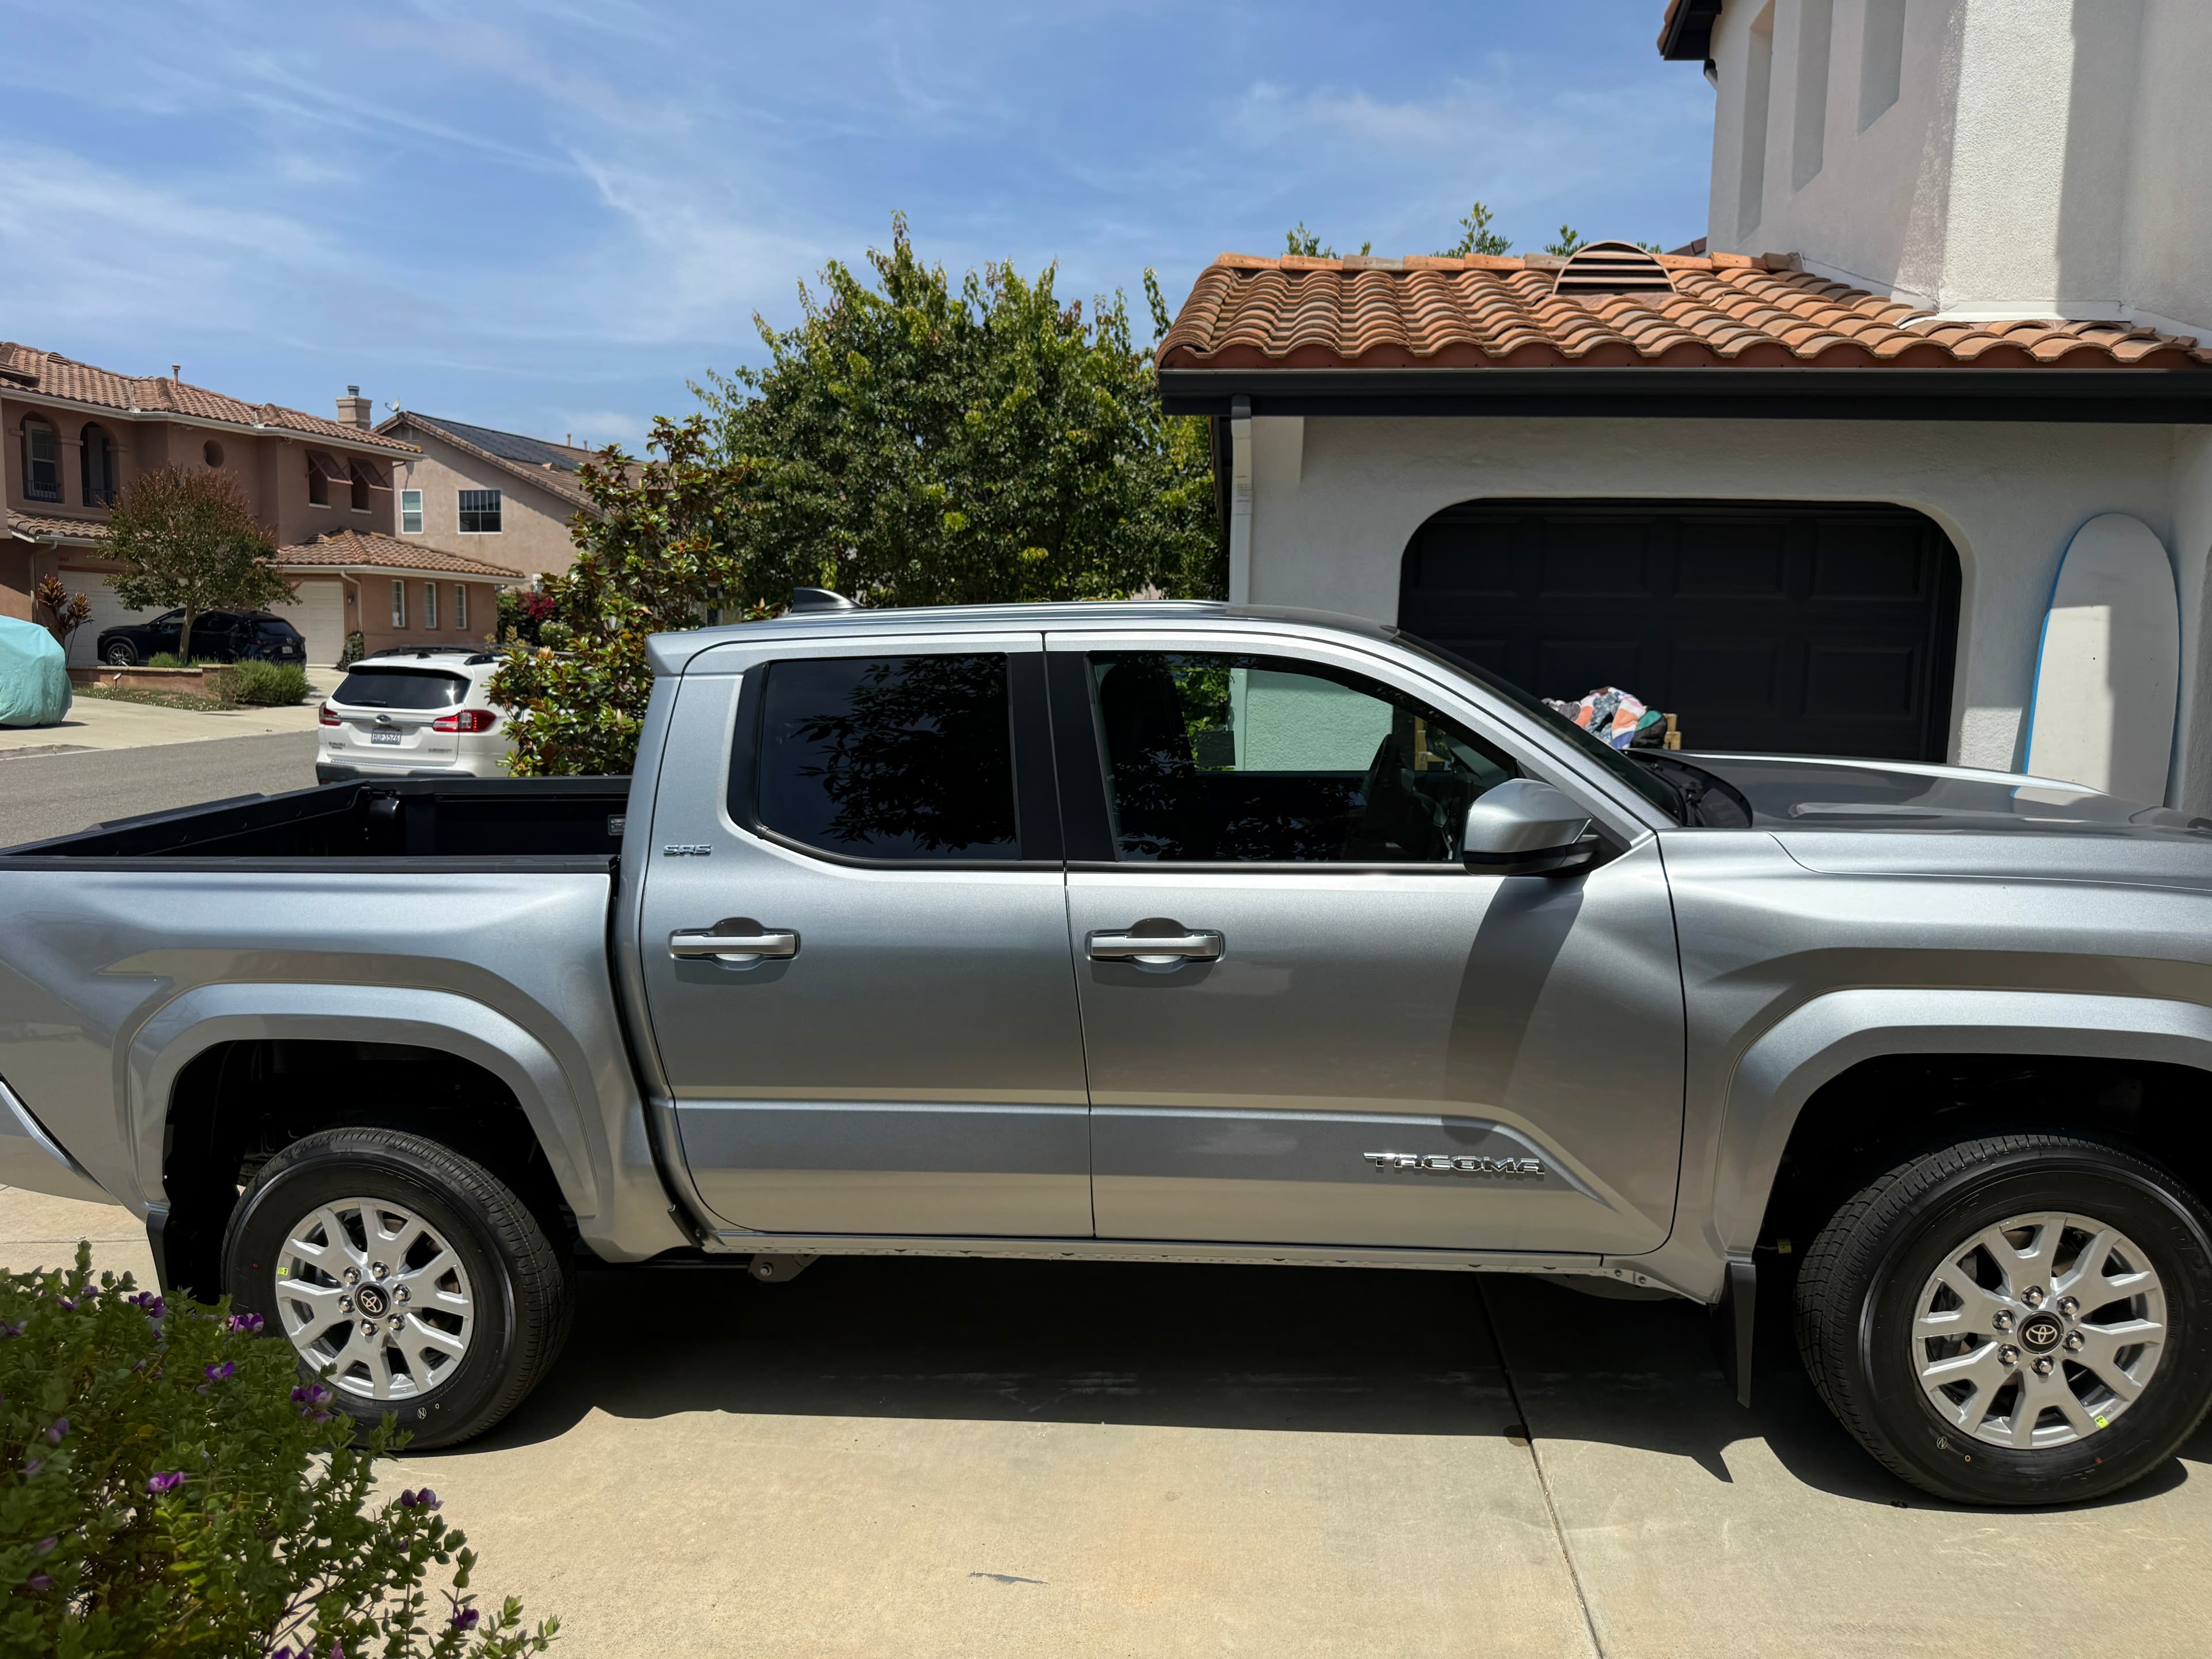
  • A silver Toyota Tacoma parked on a residential driveway
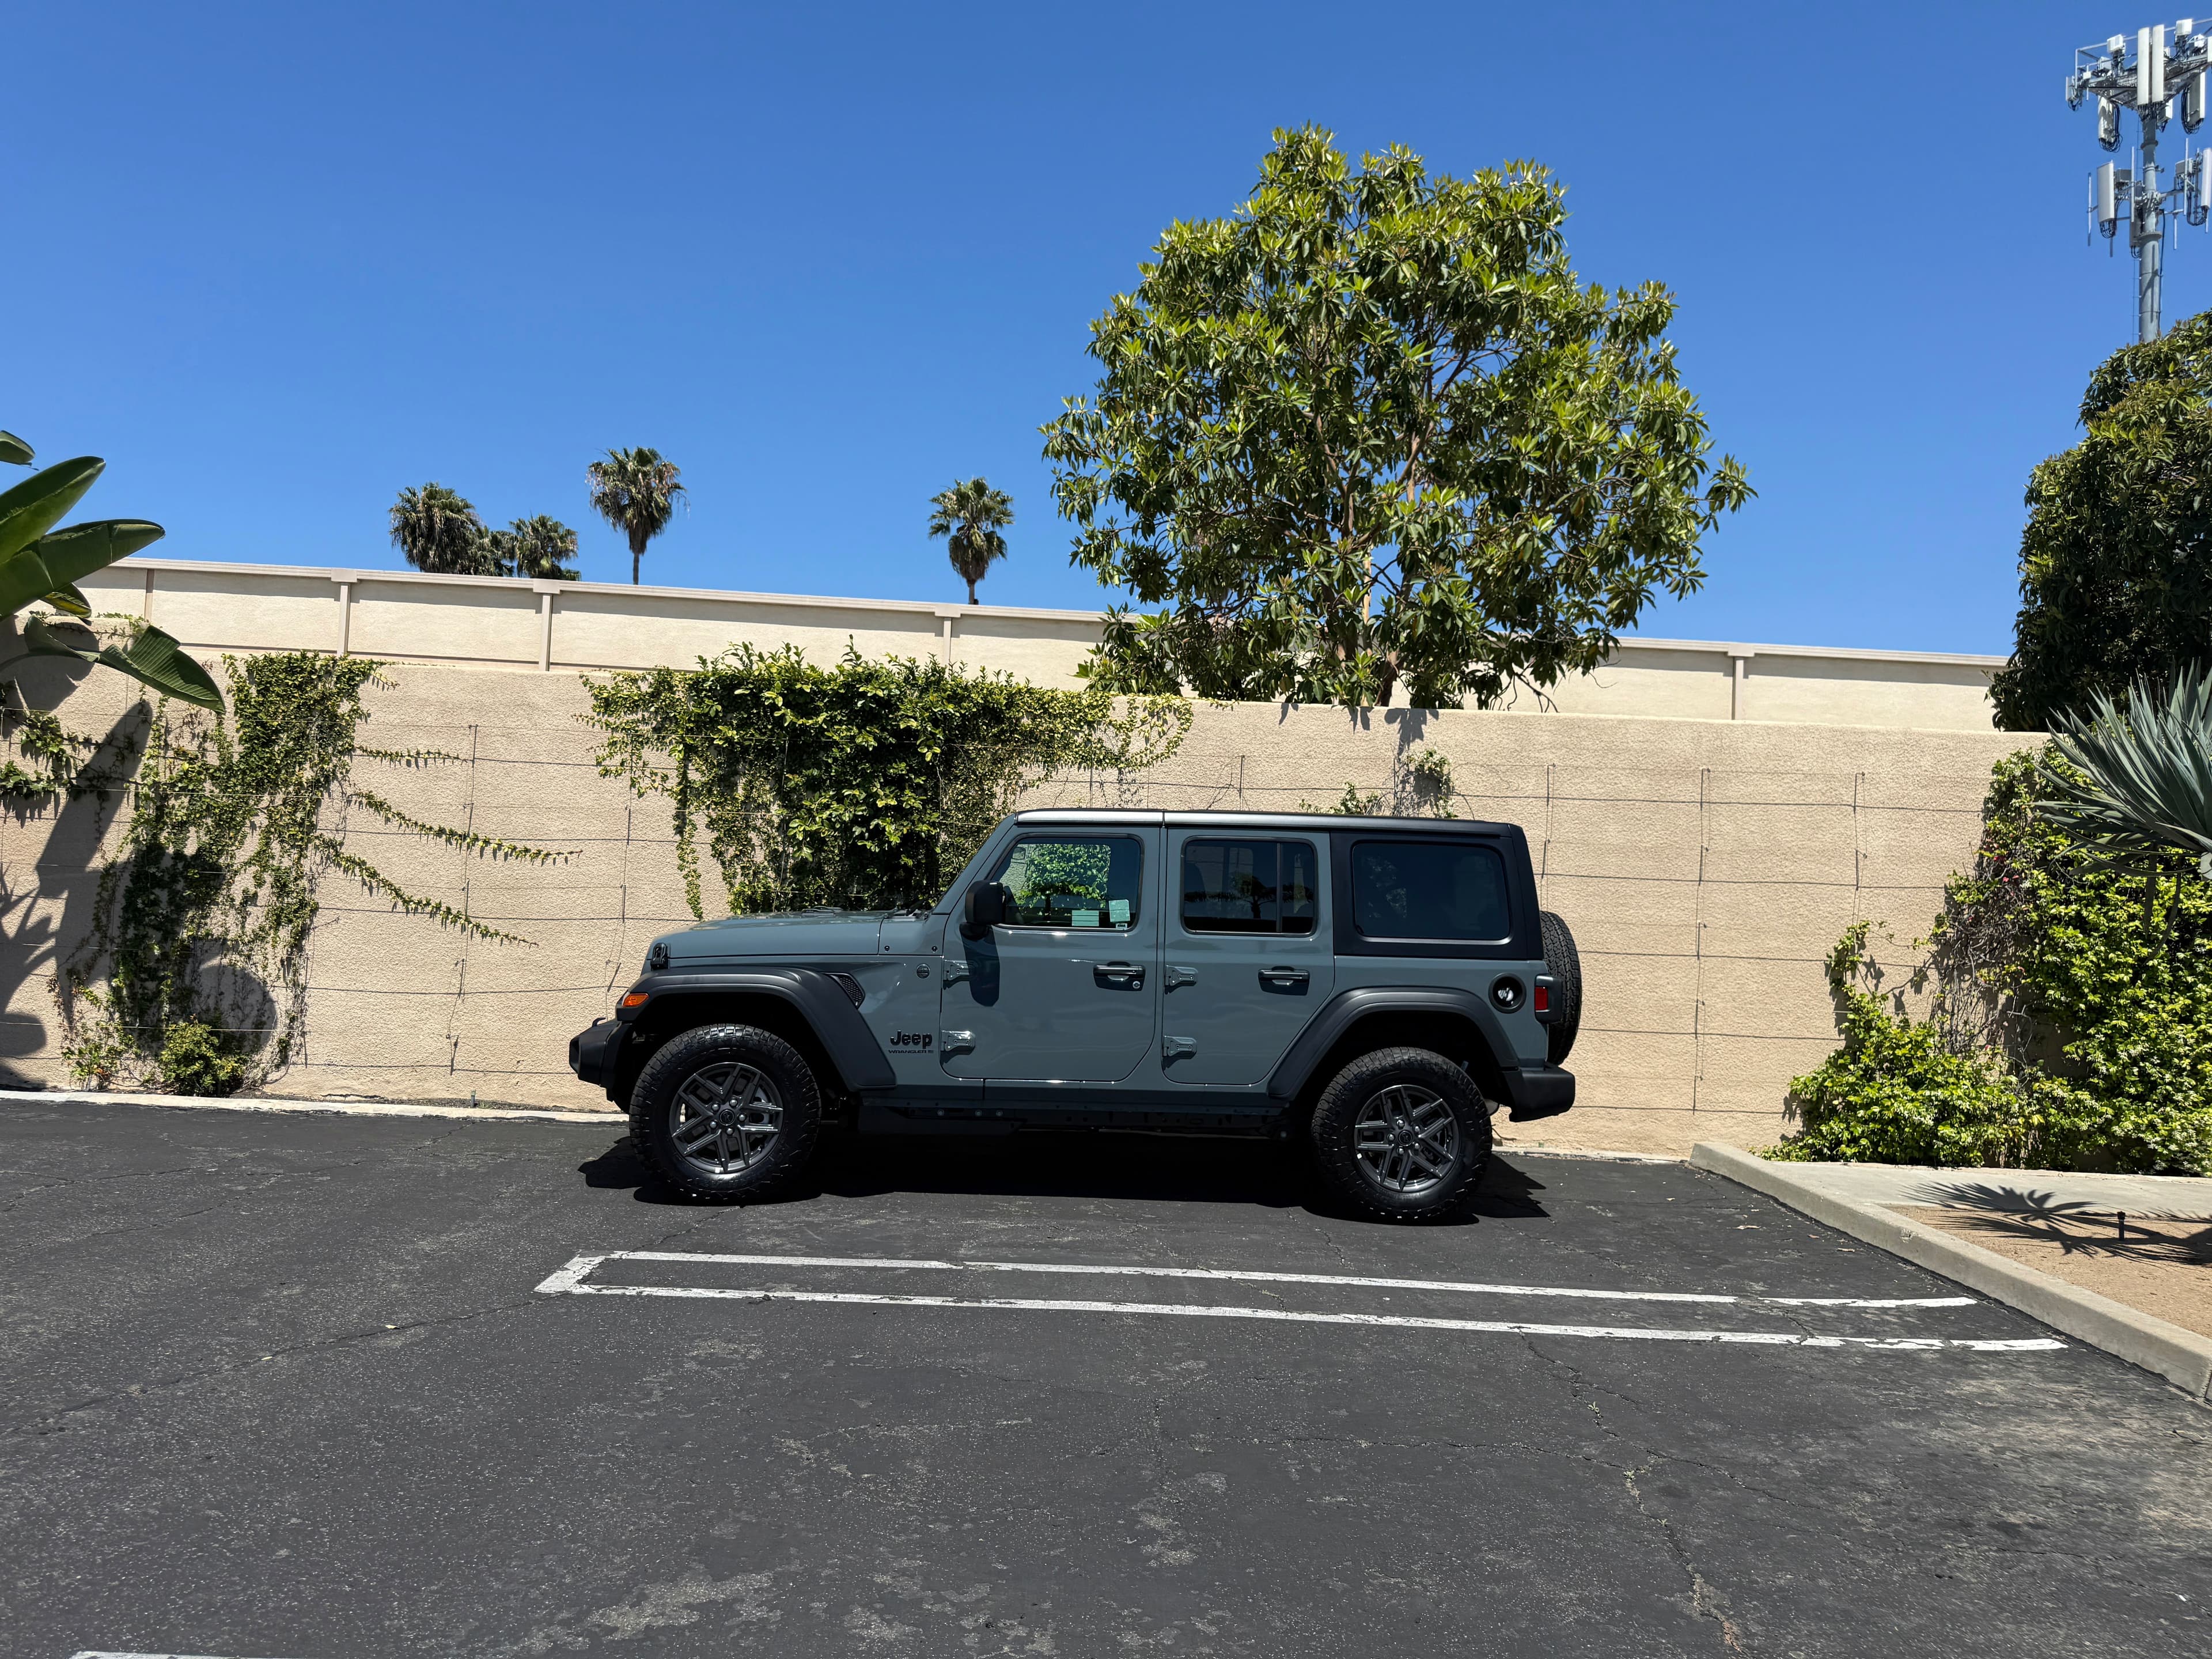
  • 2026 Grey Jeep Wrangler
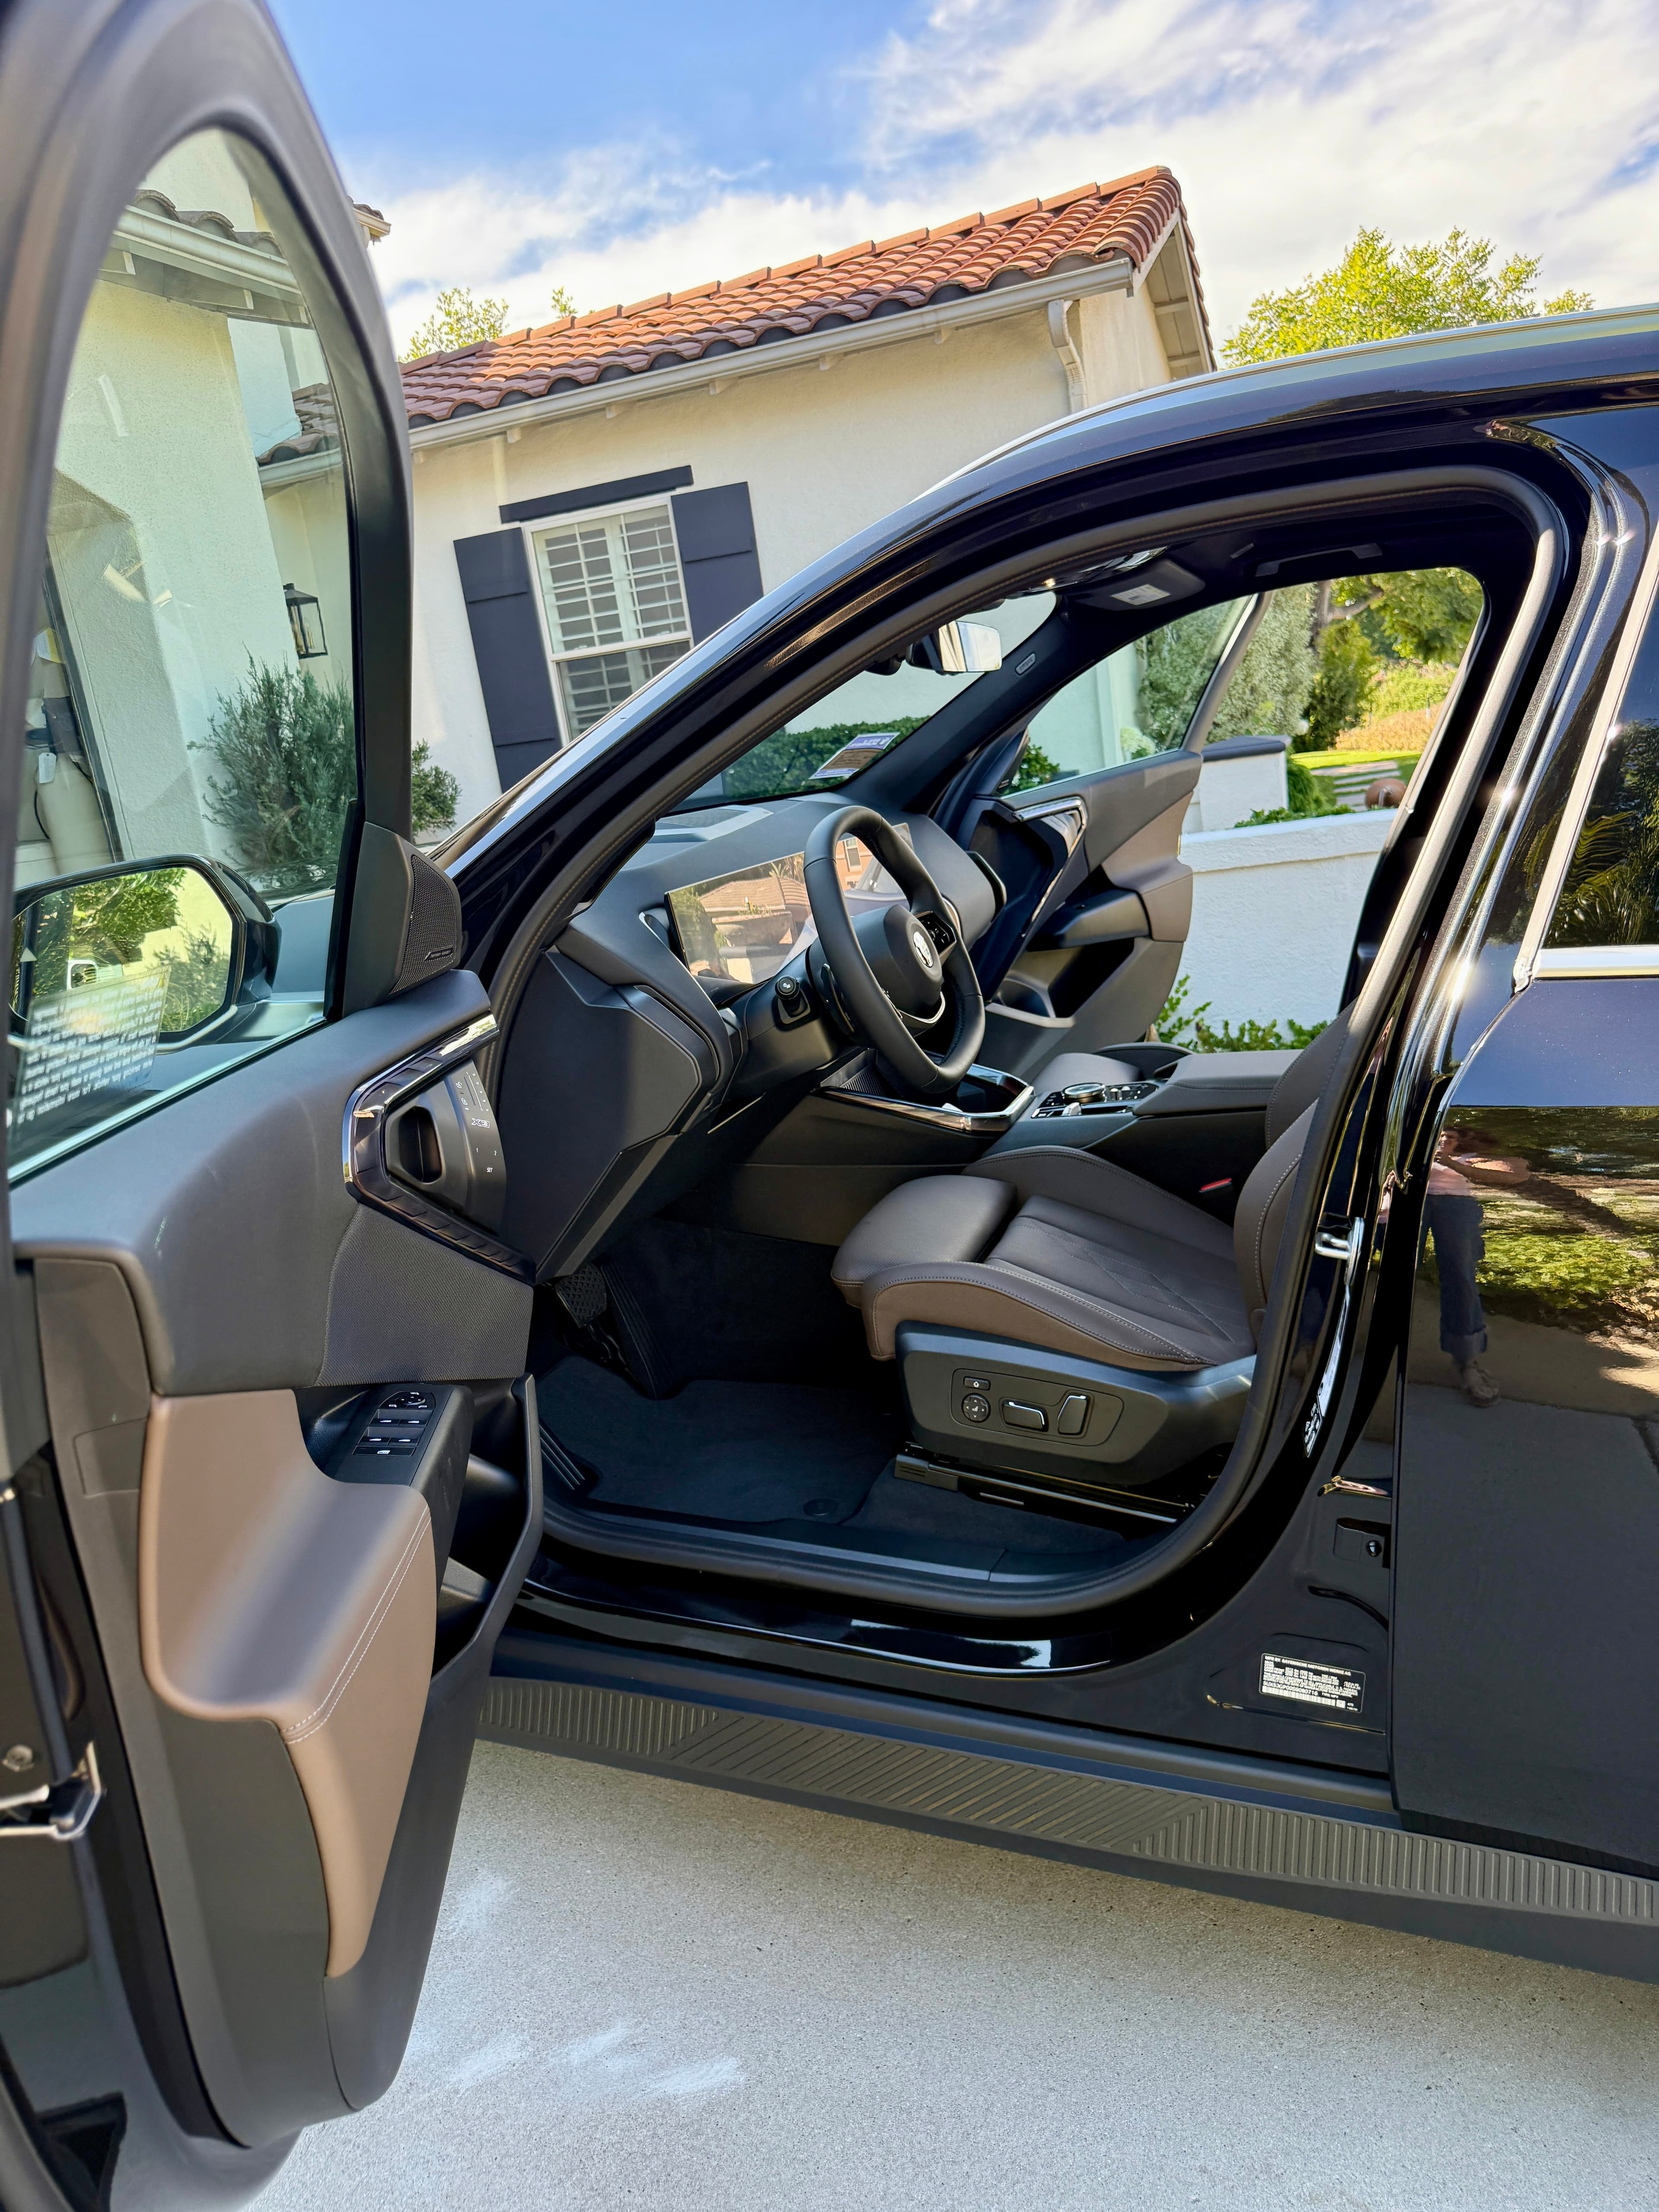
  • The open driver’s door of a black BMW on a residential driveway, showing the brown leather interior and the dashboard
  • 2026 silver honda cr-v
  • White Lexus NX350h
  • 2025 black gmc sierra
  • 2026 black Audi Q5 residential driveway
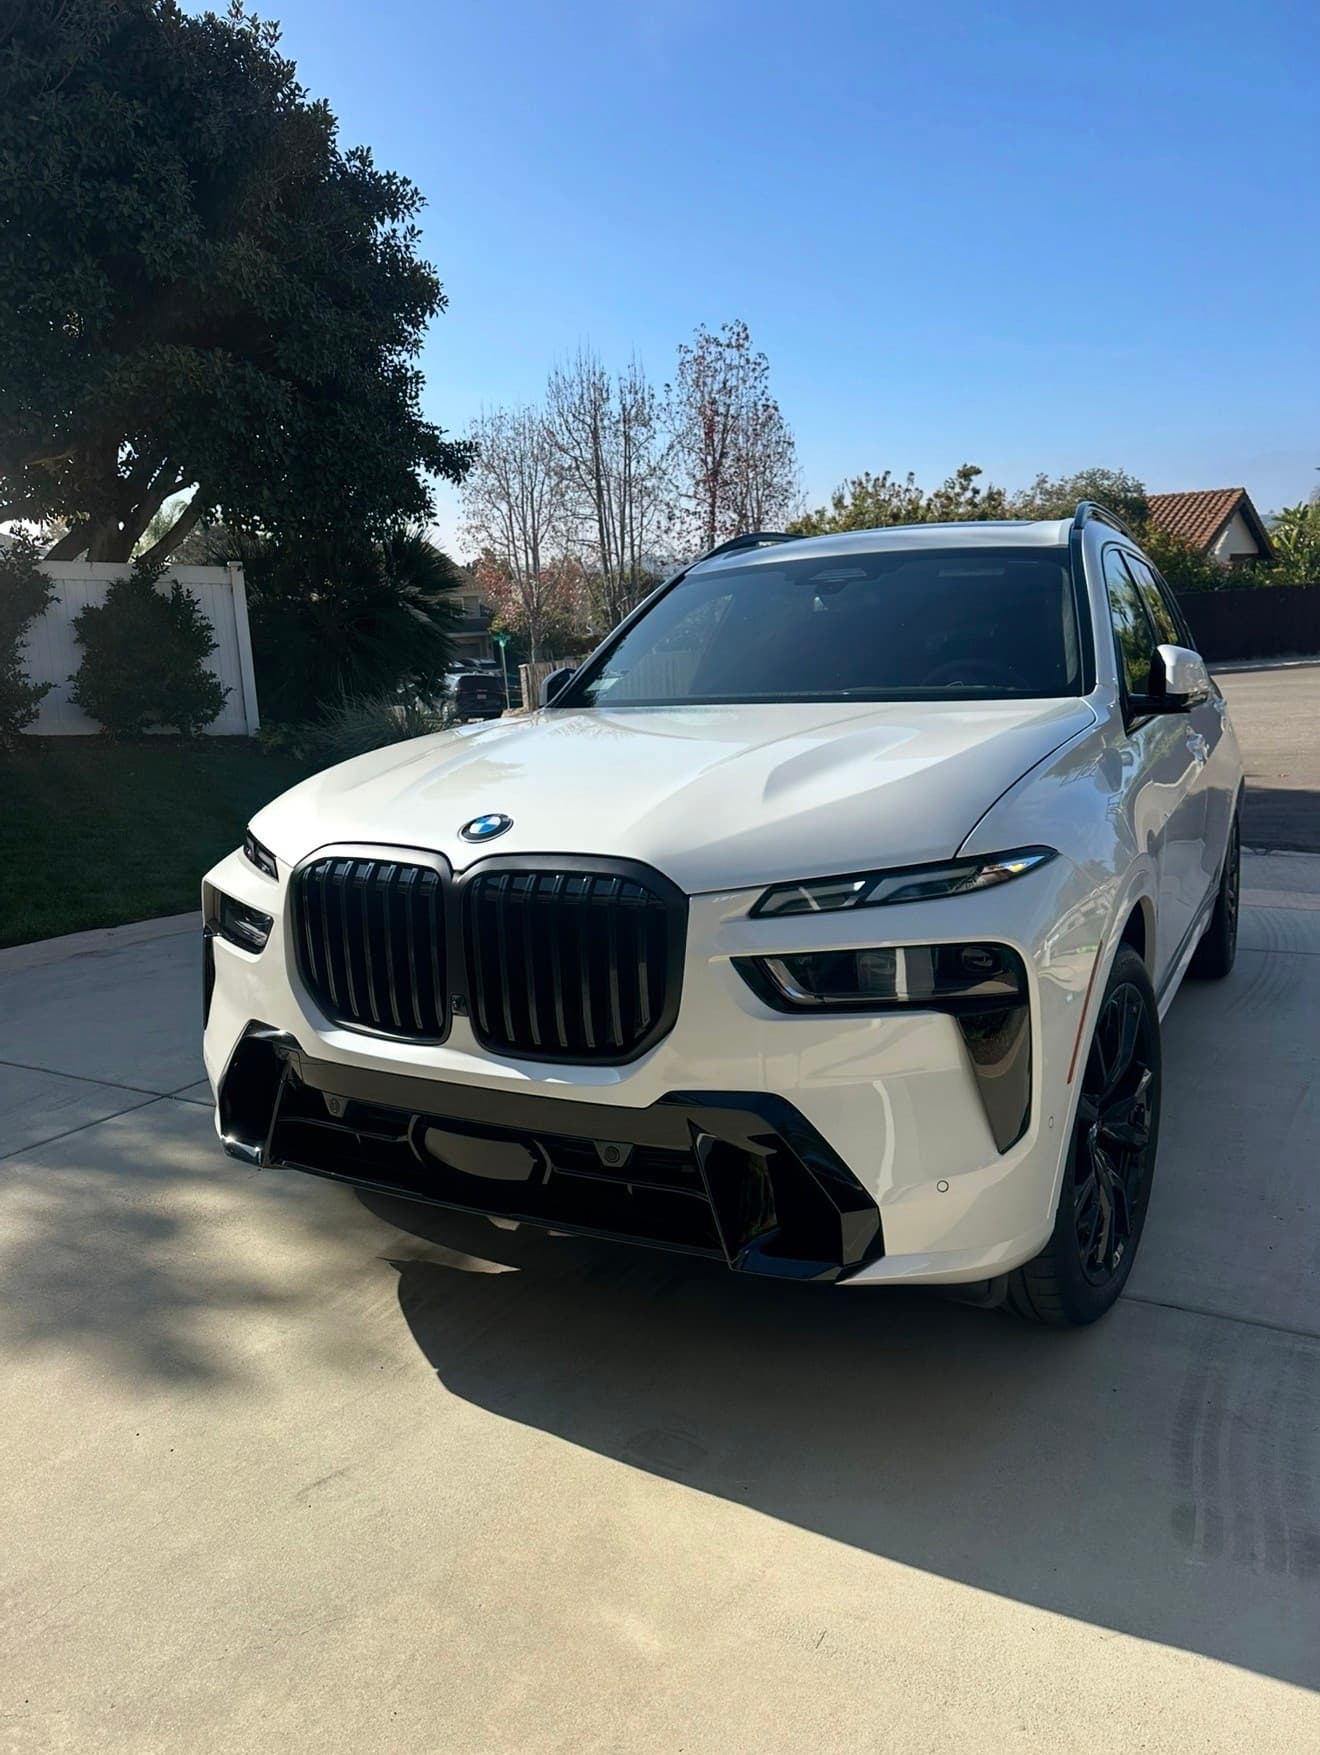
  • 2026 white bmw x7 residential delivery
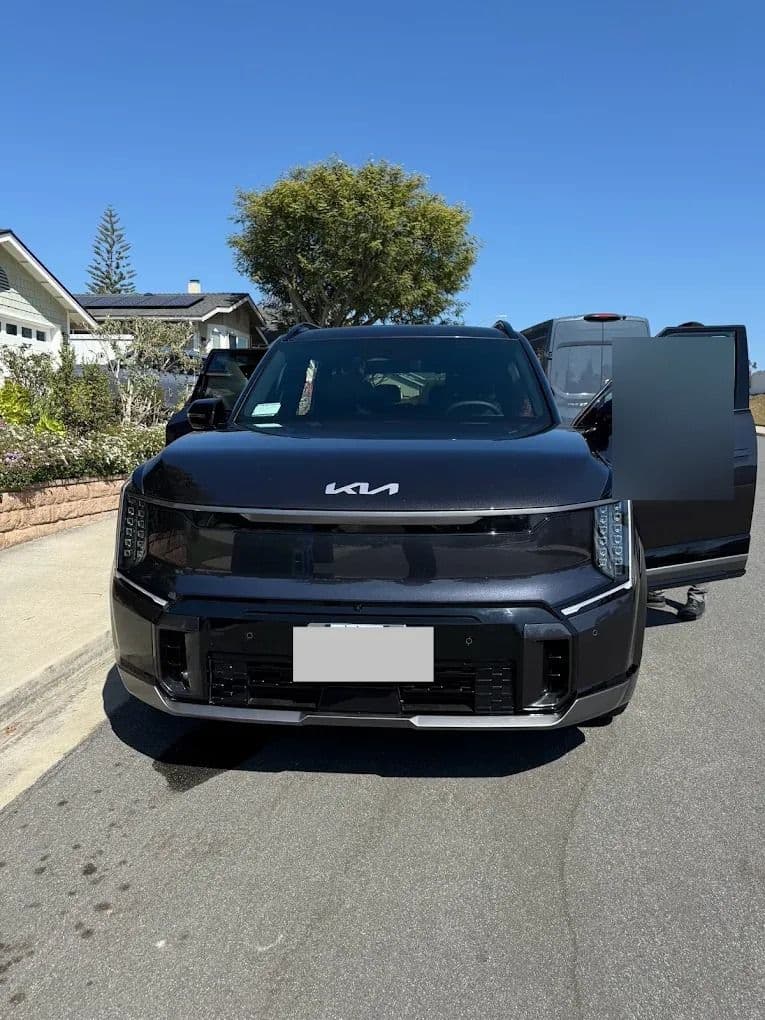
  • 2025 black KIA EV9
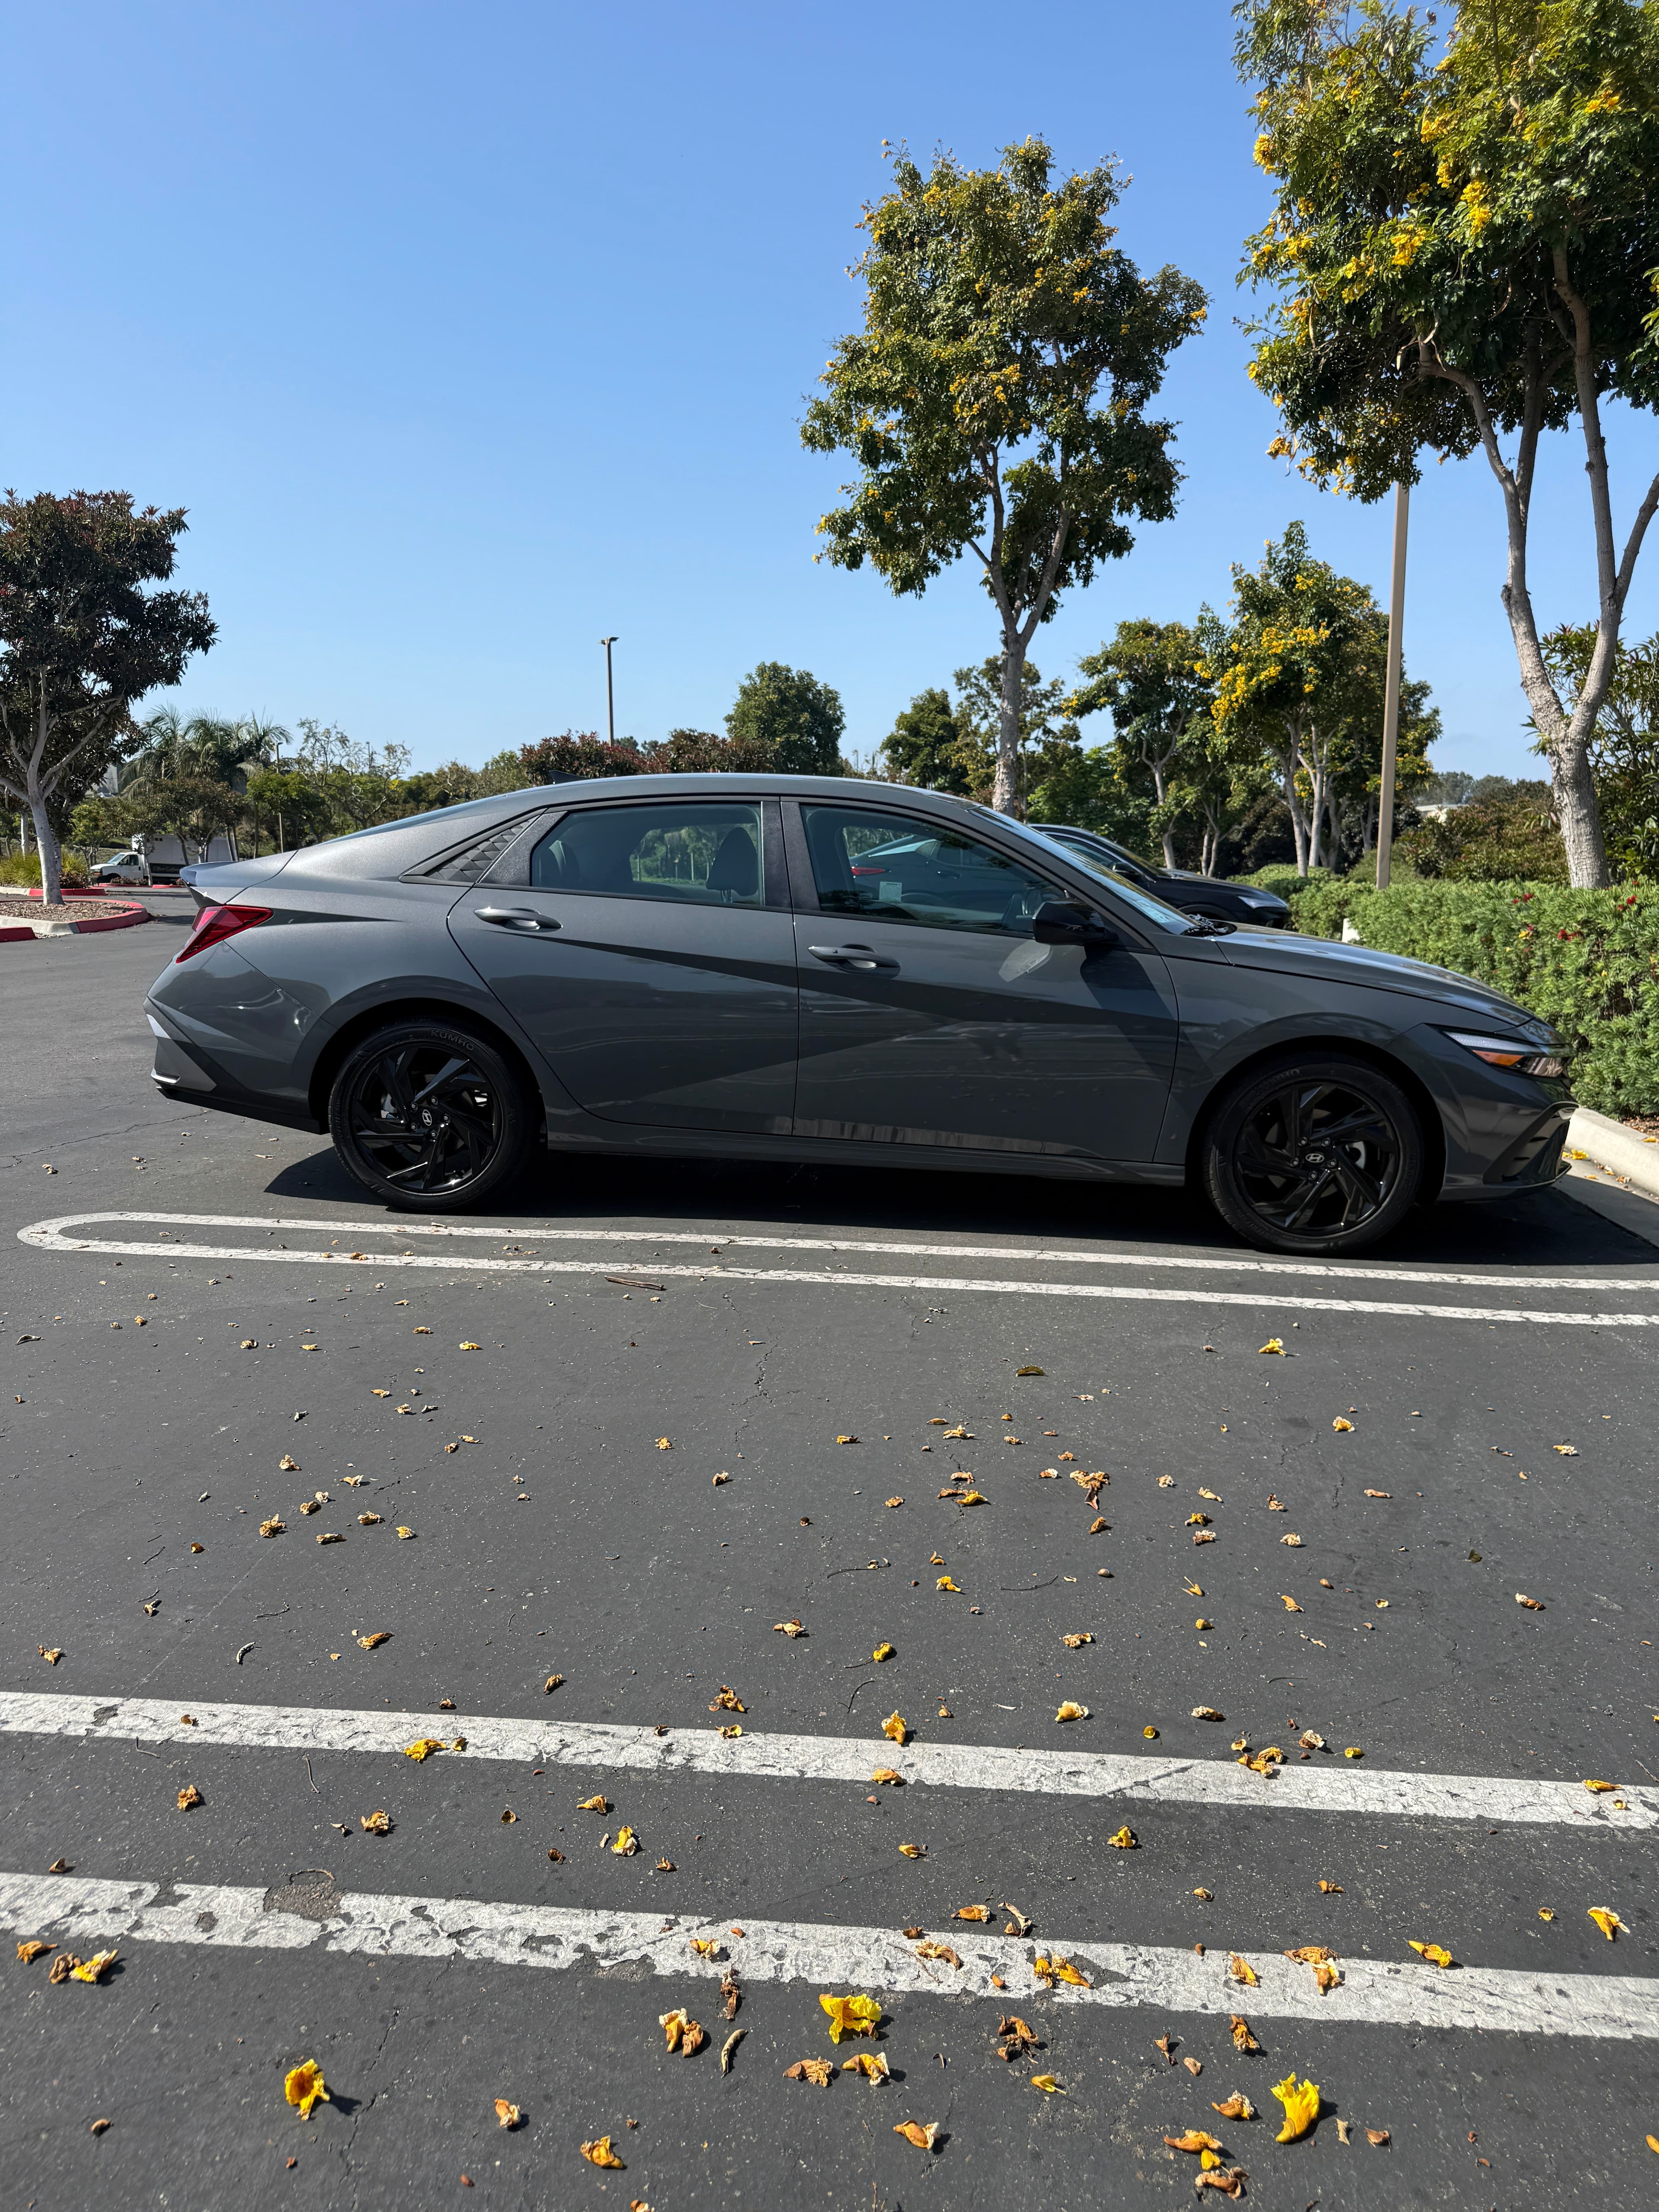
  • 2026 silver Hyundai Elantra
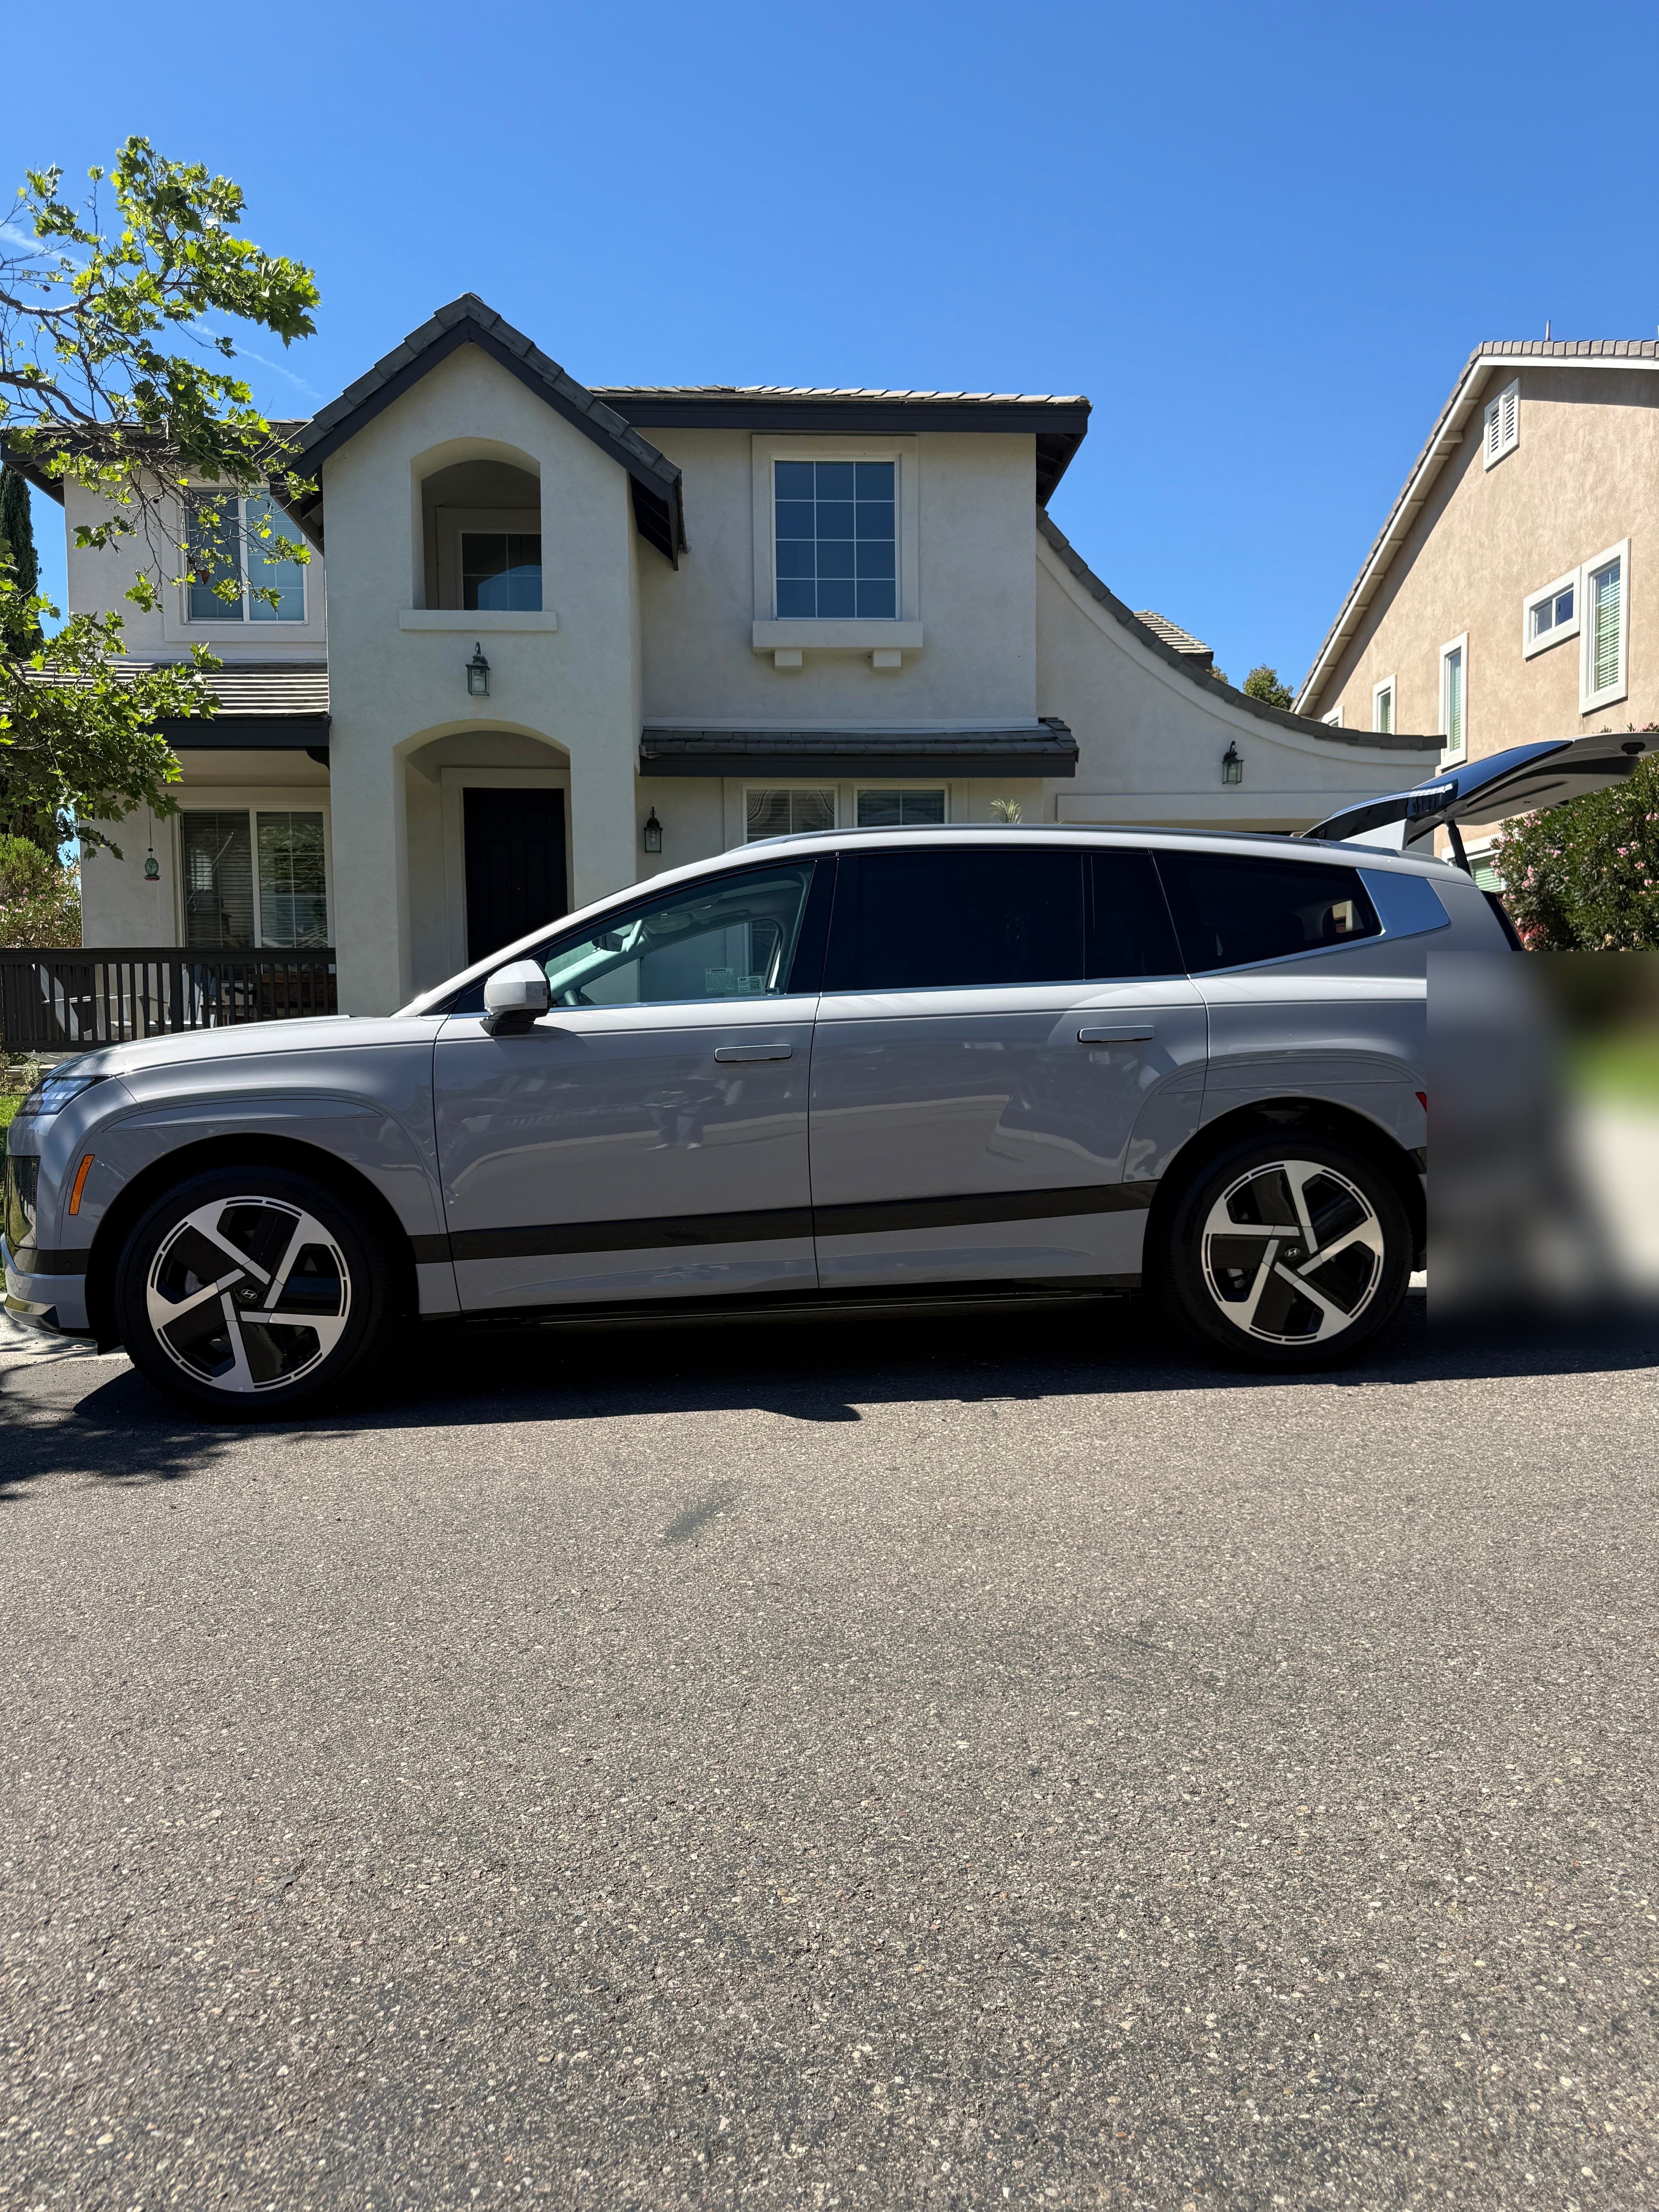
  • 2026 silver Hyundai ioniq9 in front of residence
  • 2026 grey land rover range rover sport
  • 2026 white honda cr-v residential driveway
  • Two people at the open driver’s door of a newly delivered vehicle on a residential driveway, one of them seated at the wheel
  • A red Toyota Camry parked on a residential driveway in front of an open garage
  • 2026 black Mazda CX5
  • A black Hyundai IONIQ 9 on a gravel drive beneath Monterey cypress, delivered to a client in the Bay Area
  • 2025 white mercedes-benz residential driveway
  • 2026 white land rover defender
  • 2025 black bmw x3 residential driveway
  • 2024 silver audi q5 residential delivery
  • Silver 2025 Toyota RAV4 in residential driveway

If a franchised dealer sells it in California, we source it. Tesla, Rivian, Lucid and Polestar sell direct, with no dealer to negotiate with, so those fall outside what we do.
AcuraAlfa RomeoAudiBMWBuickCadillacChevroletChryslerDodgeFordGenesisGMCHondaHyundaiInfinitiJeepKiaLand RoverLexusLincolnMazdaMercedes-BenzMININissanPorscheRAMSubaruToyotaVolkswagenVolvo
2025 black bmw x3 residential driveway

From the reviews

Working with Andrea at CarOracle made the entire car-leasing process simple and stress-free. She helped us identify the right vehicle, provided thoughtful options and industry insights, and then handled all of the heavy lifting—from sourcing the car to coordinating delivery. Every detail that would normally be time-consuming and annoying was managed seamlessly on our behalf. As a super busy family with no extra time to spare, having Andrea take this completely off our shoulders and manage the process end to end was invaluable. The experience was efficient, professional, and refreshingly easy. We couldn’t be happier with the service and highly recommend CarOracle to anyone looking for a smarter, easier way to lease or purchase a vehicle.

Melissa V. · Google · Aug 2025

Recent deliveries have included the Land Cruiser, CR-V, IONIQ 9, i4, RX and Defender. All client reviews

Lease the car on all four numbers, not the one on the ad.

Schedule a Consultation

Complimentary · 15 minutes

$299 new, $399 pre-owned and certified pre-owned, if you engage us

Frequently asked questions

I saw an ad on TV for a lease or financing deal that seems perfect for me. Why should I still use CarOracle?
Two things about an advertised offer are worth knowing before you commit. Advertisements usually exclude license and registration fees, taxes and dealer documentation fees, so the payment shown is not the payment you make. And most manufacturers enforce Minimum Advertised Price rules, which set the lowest number a dealer may publish rather than the lowest number a dealer will accept. An advertised offer is a ceiling stated as a floor. The useful question is what the same vehicle is transacting at this month, and that is a different figure.
Does CarOracle handle leasing, and how can your service help with the complexities of leasing?
Yes. A lease has more moving parts than a purchase: capitalized cost, capitalized cost reduction, residual value, money factor, term and mileage tier, and each is set a different way. Residual value and the buy-rate money factor are set monthly by the captive lender, by model, trim, term and mileage tier, and neither is negotiable at the store. The selling price, how incentives are applied, and whether the quoted money factor matches the buy rate all are. So the worksheet gets recalculated against current program data rather than accepting the quoted payment: two structures can land within twenty dollars a month of each other and differ substantially over the term.
What are the best lease deals available today?
Lease deals change constantly, but the strongest offers usually come from a combination of high residual values and manufacturer-subsidized money factors. Right now, many electric vehicles and select luxury models offer compelling lease programs, but the “best” deal depends on timing, incentives, and how the lease is structured. CarOracle evaluates current programs across brands to identify the strongest real-world lease value for each client.
Which car brands tend to have the best lease programs?
Lease strength is driven by two main factors: how well a vehicle holds its value (residual value) and how aggressively the manufacturer subsidizes the lease (money factor). Brands with strong resale values, such as Toyota, Lexus, Honda and Subaru, often lease well. Luxury and EV brands may also offer attractive leases when manufacturers lower money factors or support lease programs to drive demand. Because incentives change frequently, the “best” lease brand can vary by model and timing.
Given the information available online, what value does CarOracle’s Auto Leasing Program provide?
An online tool can show you a lease offer. It cannot tell you whether the money factor in it matches the lender’s buy rate, whether the incentives you actually qualify for have been applied, or whether the capitalized cost includes products you did not ask for. Those three are where a lease quote goes wrong, and all three are checkable against current program data before anybody signs anything.
How is CarOracle compensated for its auto leasing program and auto broker services?
Service Fees: CarOracle is a paid auto leasing service. Clients pay a flat consultation fee, and we may also receive compensation from the selling dealer. Regardless of compensation source, we are a California-licensed dealer operating with an auto broker endorsement, and our obligations run to the client throughout the transaction.
Where can I find the best lease deals near me through CarOracle’s Auto Leasing Program?
CarOracle sources lease deals for clients throughout California, with active operations in the Bay Area, Los Angeles, Orange County, Riverside County, Sacramento and San Diego. The search runs across the broader marketplace rather than a single dealer, so where you live sets where the car is delivered and not where it comes from.
How does CarOracle structure and optimize car leases for clients?
Around the four variables that actually set the cost: money factor, residual value, incentives and the mileage tier. Dealer-provided terms are verified against current program data. Incentives are applied where you qualify rather than where they are advertised. Term and mileage are matched to how you actually drive, using your last oil change record as a starting point rather than a guess. A low advertised payment can hide a marked-up money factor or a mileage tier you will exceed, which is why the payment is the last number to compare and not the first.
How Does Car Depreciation Impact My Lease or Purchase?
Car depreciation is the loss of a vehicle’s value over time, and it affects leasing and buying very differently. When you lease, you primarily pay for depreciation during the lease term. Vehicles with higher projected resale value (higher residuals) typically result in lower lease payments. When you buy, depreciation directly affects your long-term ownership cost and resale value. Vehicles that depreciate quickly can cost significantly more over time when you sell or trade them in. Understanding depreciation helps determine whether leasing or buying makes more financial sense for a given vehicle.
What is a money factor in a lease, and how does it compare to APR?
The money factor is the interest rate used in a lease, expressed as a small decimal rather than a traditional APR. It determines the finance charge portion of your lease payment. To compare a money factor to an APR, multiply it by 2,400. For example, a money factor of 0.0025 is equivalent to a 6% APR. Because even small changes in the money factor can materially affect your payment, understanding it is critical when evaluating lease offers.
Is leasing with the intent to buy a good financial strategy?
Leasing with the intent to buy can make sense in certain situations, but it’s not always the most cost-effective path. It works best when the lease is structured well, the residual value is reasonable, and the vehicle’s long-term ownership value aligns with your goals.
What is GAP Insurance?
GAP insurance (Guaranteed Asset Protection) covers the difference between what your vehicle is worth and what you still owe if it’s totaled or stolen. It protects you from having to pay out of pocket when depreciation causes a “gap” between market value and your loan or lease balance